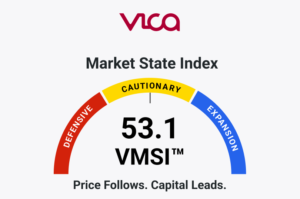
The VMSI™ Composite declined to 51.7 (−1.4), while IC-VMSI™ increased to 64.4 (+0.4) and ICMI™ eased to 48.9 (−0.2), as stronger ETF issuance and reserve recovery contrasted with weaker equity participation and less supportive risk pricing. Fragile Stabilization remains the PLMT™ assessment and Defensive Capital Migration remains the ICMI™ classification, separating observable implementation from evidence of lasting ownership and market absorption.
VMSI™ Snapshot
Week Ending November 6, 2026 · Prior comparison: October 30, 2026.
Component
Current
Prior
△ (w/w)
Interpretation
VMSI™ Composite
51.7
53.1
−1.4
Cautionary. Weaker participation and volatility conditions contrasted with stronger issuance and reserve liquidity.
Momentum
56.9
59.5
−2.6
Short-horizon breadth contracted; intermediate participation and equal-weight resilience supplied counterevidence.
Liquidity
52.1
50.7
+1.4
Reserves recovered and secured-funding pricing improved at the endpoints; broader financing access remained unconfirmed.
Volatility & Hedging
51.1
53.8
−2.7
Higher equity volatility and more adverse modeled gamma indicated less favorable conditional hedging sensitivity.
Safe Haven Demand
53.0
52.2
+0.8
Gold and Treasury-duration prices strengthened without identifying defensive subscriptions or owners.
Advanced Framework Layer
Advanced Framework Layer scores are proprietary VICA Research measures. Public reporting presents framework state and directional change; underlying construction methodology remains proprietary.
Framework
Score / State
Weekly Change
Institutional State
SPI™
57.2
−2.6
Weaker 20- and 200-day breadth contrasted with stronger 50-day participation and relative equal-weight resilience.
CMX™
50.1
−2.7
All-expiration modeled gamma deteriorated despite improvement in the nearest-expiry subset.
PDCS™
60.7
+0.6
Stronger creations and reserve recovery supported deployment; credit and execution confirmation remained uneven.
GFP™
54.8
−1.8
China large-cap resilience contrasted with Japan and broad international weakness.
IC-VMSI™
64.4
+0.4
Flow momentum improved; ownership persistence, active allocation and absorption were less directly observed.
PLMT™
Fragile Stabilization
Unchanged
Implementation resilience opposed deterioration; participation and risk pricing did not confirm expansion.
Structural Conclusion: Stronger implementation did not establish a proportionate improvement in the conditions supporting maintained exposure.
Signal Integrity
Market prices and established moving-average breadth compare October 30 and November 6 Friday closes. ETF Action’s five-session issuance and ICE credit spreads compare October 29 and November 5. Federal Reserve balances are weekly averages ending October 28 and November 4; funding rates use the matched Thursdays. Thursday-ended flows cannot establish Friday’s investor response.
The ETF asset comparison uses the same vendor’s category labels, not an independently verified fixed set of funds. Its AUM-minus-flow residual is a diagnostic requiring reconciliation, not measured performance, outflows or lost financing capacity.
Gamma is modeled sensitivity, not observed inventory. Matching an expiration cutoff does not hold contracts, spot or implied volatility constant. VIX and gamma share options-market inputs; their agreement is not independent validation of a dealer mechanism.
Price-based ETF comparisons exclude distributions. Missing ownership or execution observations constrain attribution, not the sign of a score. Supplemental diagnostics do not acquire scoring weight without separate approval.
Structural Conclusion: Observation windows, universe consistency and measurement independence bound every institutional inference.
Executive Summary
The constructive change was stronger issuance alongside reserve recovery. The adverse change was weaker participation and higher equity volatility. These developments occurred in distinct systems and cannot be reduced to one uniformly improving or deteriorating condition.
Two proposed shortcuts fail. Positive ETF creations do not identify persistent institutional owners; declining AUM does not disprove their persistence. Similarly, near-expiry gamma relief does not describe the entire modeled book, but its broader deterioration does not prove additional dealer selling.
Credit chronology further qualifies the deterioration case. Most of the prescribed high-yield widening occurred on October 30, although renewed November 5 pressure prevented a conclusion of uninterrupted repair.
Structural Conclusion: The week strengthened the implementation evidence while increasing the importance of independent ownership, financing and execution tests.
Market Structure
The closing-price record shows the S&P 500 falling 7,580.07 → 7,376.86, approximately 2.68%. RSP declined approximately 1.04%, outperforming the capitalization-weighted index by 1.65 percentage points, calculated before rounding. Relative resilience was not a positive absolute return.
S&P 500 participation above the 20-day average declined 69.18% → 59.76%; above the 50-day average increased 60.23% → 61.55%; and above the 200-day average declined 59.44% → 55.97%. The respective changes were −9.42, +1.32 and −3.47 percentage points.
The surviving majorities are meaningful counterevidence to a wholesale breakdown. Aggregate percentages cannot establish whether the same constituents retained their trends, and the three horizons are overlapping measurements of one universe.
Structural Conclusion: Absolute participation weakened even as intermediate breadth and relative equal-weight performance resisted a uniform deterioration interpretation.
Credit & Liquidity Conditions
Investment-grade OAS widened 89 → 93 basis points and high yield 326 → 348 over the prescribed Thursday window. CCC-and-lower narrowed 1,325 → 1,320, opposing a uniform quality-tier deterioration claim.
High yield had already reached 344 basis points on October 30. Thus 18 of the net 22 basis points occurred that day; the subsequent net change through November 5 was four. Spreads nevertheless widened 332 → 348 on November 5. An unchanged endpoint convention must not obscure the intervening repair and reversal.
Weekly-average reserves increased $36.318 billion to $2,930.088 billion. Treasury General Account balances declined $42.552 billion, while Reserve Bank credit fell $4.250 billion. Reserve recovery was not broad Federal Reserve asset expansion.
SOFR declined 3.94% → 3.92%, with EFFR unchanged at 3.88%. Their spread narrowed from six to four basis points, after reaching nine during the interval.
Structural Conclusion: Reserve and funding-rate endpoints improved; uneven credit repricing did not independently establish impaired borrowing access.
Positioning & Convexity
VIX increased 19.42 → 25.64, despite Friday’s retreat from 28.18. The vendor-reported VIX/VIX3M ratio rose 0.935 → 1.042, indicating higher near-term volatility pricing relative to the three-month reference.
I ♡ VOL’s dated all-expiration SPX gamma estimate changed −$53.9 billion → −$85.8 billion per 1% index move. Its within-seven-day estimate improved −$29.1 billion → −$22.7 billion. These nested windows are not additive or independent.
The model describes potential hedging sensitivity under assumed dealer positions. Its relationship to actual execution requires separate evidence; higher implied volatility cannot independently validate a gamma estimate partly determined by that volatility.
Structural Conclusion: Conditional sensitivity deteriorated overall, without identifying actual dealer inventory or realized forced transactions.
Flow & Allocation Behavior
Equity ETF net creations increased $27.38 billion → $45.80 billion; fixed-income creations increased $13.61 billion → $16.36 billion. Calculated issuance relative to each period’s reported AUM rose approximately 0.2150% → 0.3615% for equities and 0.4923% → 0.5877% for fixed income.
Equities led in dollar activity; fixed income retained greater asset-normalized intensity. Neither comparison identifies transfers by common investors.
The two ETF Action reports also show declining equity-category AUM. The detailed reconciliation appears in the first discovery. The important distinction is between net issuance, asset valuation and the identity of the resulting holders.
Structural Conclusion: Implementation increased in both asset classes; its distribution and persistence require different observations.
Structural Participation Integrity
SPI™ declined to 57.2 from 59.8. Breadth deterioration and higher volatility supplied adverse evidence; the stronger 50-day reading and reserve recovery supplied contradictions.
The five domains remain breadth, concentration, volatility compression, liquidity mechanics and participation elasticity. Equal-weight outperformance informs concentration-related price behavior, not institutional order capacity.
For elasticity, the relevant supplementary test is whether comparable orders encounter different spreads, displayed depth or execution shortfall at similar volatility and times of day. Breadth cannot supply those measurements by proxy.
Structural Conclusion: Participation weakened; absorption capacity remained a separate, incompletely observed question.
Global Propagation Conditions
The matched international price record shows VEA −2.22%, EFA −1.43%, VWO −0.40% and IEMG −2.76%. VEA underperformed VWO, while EFA outperformed IEMG: a universal developed-versus-emerging rotation is not supported.
FXI gained approximately 5.65%, while EWJ declined 5.00%. Country, currency and sector differences can produce this dispersion without direct transfers between those markets.
A currency-adjusted regional comparison would test one alternative explanation. Comparable subscriptions or financing observations would address a different question: whether cross-border implementation accompanied the price differences.
Structural Conclusion: Geographic dispersion was observable; synchronized allocation or common withdrawal was not.
Advanced Signal Layer
The established definitions are unchanged. The price-based relationships below are calculations from the matched closing-price record, not independent capital-flow measurements.
CQR™: Approximately 1.3466 → 1.3535. The LQD/HYG relationship includes duration, distribution and composition effects; it does not isolate credit quality.
HPR™: Approximately 0.468, calculated from published rounded ratios of 0.59 and 1.26. Historical matching remains qualified. Options volume does not identify buyers, opening positions or net protection.
DFR™: Approximately 2.012 → 2.800. Both issuance series increased; the ratio does not establish bond-to-equity substitution.
GPR™: Approximately 1.251 → 1.228. The established VEA/VWO pair weakened; more favorable alternative pairings cannot replace it.
Structural Conclusion: Relationships refine the existing evidence without creating additional independent confirmation.
CMX — Convexity Metrics Index
CMX™ declined to 50.1 from 52.8. The useful refinement is expiration coverage, not a stronger assertion about dealer identity.
A common calendar exclusion provides a narrower comparison than changing seven-day windows. Its results, limitations and execution test are specified in the second discovery.
A fixed-calendar comparison remains sensitive to valuation and contract composition. Only a common-contract, common-input reconciliation could separate those effects from modeled position changes; even that would not observe dealer ownership directly.
Structural Conclusion: Expiration-aware analysis improves the transmission question, not the certainty of the positioning estimate.
PDCS — Pre-Deployment Capital Signals
PDCS™ increased to 60.7 from 60.1. Greater creation activity and reserve recovery supported deployment initiation.
Persistence requires a separate test over subsequent, comparable five-session windows. Repeated creations should be distinguished from reversals concentrated in a few funds, then assessed alongside financing and participation.
Two stronger aggregate readings demonstrate repeated implementation, not the holding duration of the investors behind it. Concentration or reversal would qualify the interpretation without retroactively negating the original transactions.
Structural Conclusion: Deployment initiation improved more clearly than persistence could be established.
GFP — Global Propagation Framework
GFP™ declined to 54.8 from 56.6. The established relative relationship and broad international returns supplied less supportive evidence; China was a substantive exception.
The next diagnostic is a fixed-universe comparison separating local-equity returns from currency translation, followed by region-level flow or funding evidence where available. Additional overlapping ETFs cannot substitute for either step.
Structural Conclusion: Global propagation remained selective rather than broadly synchronized.
PLMT — Post-Linear Market Structure
VICA retains Fragile Stabilization. Active implementation, reserve recovery and surviving intermediate participation opposed a structural-deterioration interpretation. Weaker breadth, higher volatility and adverse modeled sensitivity limited the expansion case.
These competing observations do not prove that a specific financing or positioning constraint was binding. They test the framework’s implications rather than establish the theory from one reporting week.
Expansion requires durable participation joined by deployment and financing confirmation. Deterioration requires persistent participation weakness with fresh, corroborated credit, funding or execution pressure. These are prospective tests, not new scoring thresholds.
Structural Conclusion: The regime assessment remains unchanged because neither competing transition has sufficient confirmation.
What Information Did the System Gain This Week?
The reserve-contraction premise weakened; implementation acceleration persisted. Those are revisions to the prior information set, not reasons to carry its narrative forward unchanged.
Three narrower findings deserve investigation: issuance and measured asset values diverged; later-expiration modeled sensitivity was not described by near-expiry relief; and nominal-yield relief did not include lower real-yield benchmarks.
Each has a different evidentiary status. The first is an unreconciled accounting diagnostic, the second a model-conditioned observation, and the third a yield decomposition. None independently establishes ownership persistence or causal transmission.
Structural Conclusion: Information improved through better separation of measured states and testable explanations, not additional indicator agreement.
Three Hidden-State Discoveries
The findings below identify consequential measurement distinctions. Their proposed ownership, execution and financing implications remain subject to the stated tests.
1. Share creation and the measured asset base moved in opposite directions.
Observation. Reported equity ETF AUM declined $12,731.96 billion → $12,669.88 billion, a $62.08 billion decrease, alongside $45.80 billion of five-session net creations. The calculated AUM change less issuance is −$107.88 billion.
Mechanism and evidence. This is an unreconciled residual from category snapshots, not a measured investment loss. The same category label does not guarantee identical funds or classifications. Valuation, distributions and universe changes must be separated before attributing it. The independent equity-price decline supports investigating valuation, but its different observation window cannot reconcile this residual.
Contradiction. Long-term investors can retain newly created shares while market values fall. Moreover, the source’s one-day VOO, IVV and SPY flows net to approximately +$5.60 billion, despite opposing fund-level directions. Those offsets neither negate new investment nor identify transfers by the same owners.
Confirmation: A fixed-fund, matched-date reconciliation of NAV, shares outstanding, distributions and corporate actions explains the residual predominantly through valuation while verifying positive net creations. Ownership persistence requires separate investor evidence.
Falsification: Universe or cutoff adjustments remove the apparent divergence, or constituent records contradict the aggregate creation measure. A subsequent AUM recovery would not falsify the historical arithmetic.
Capital Consequence: Separate share formation from valuation in the exposure review. Neither strong creations nor falling AUM alone justifies changing an assumption about owner retention or executable market capacity.
Structural Conclusion: The record establishes a stock-flow divergence, not weak ownership persistence or impaired absorption.
2. Near-expiry relief did not describe later-expiration modeled sensitivity.
Observation. Excluding all expirations through November 20, the vendor’s modeled SPX gamma at each date’s spot changed from approximately −$2.6 billion to −$34 billion per 1% index move. This uses a common calendar cutoff, unlike rolling seven-day comparisons.
Mechanism. Under the vendor’s assumptions, adverse conditional sensitivity remained outside the nearest expirations. The result does not show that dealers added positions: spot, implied volatility, time and the included contracts changed.
Independent context and contradiction. Credit repricing supplies separate risk-market context, not verification of dealer transmission. VIX and gamma are related options measures, not independent confirmations. Friday’s partial model improvement also contradicts uninterrupted deterioration.
Confirmation: Common-contract analysis, revalued at common spot and volatility assumptions, identifies what changed; independently observed spreads, depth or price impact then support the proposed amplification under comparable shocks.
Falsification: Reconciliation explains apparent repositioning through valuation or composition, or repeated comparable shocks fail to exhibit the proposed execution effects. Neither outcome erases the originally reported model state.
Capital Consequence: Review hedge expirations and execution assumptions across the relevant horizon. Do not infer that the next expiry clears broader sensitivity, or derive a trade size from an unverified inventory estimate.
Structural Conclusion: The model’s expiration structure matters, but the corresponding dealer trades and market impact remain unobserved.
3. Nominal Treasury relief did not include real-yield relief.
Observation. The ten-year nominal par yield declined 4.94% → 4.86%, while the real par yield increased 2.60% → 2.63%. Their approximate differential narrowed 2.34% → 2.23%. Five-year nominal and real yields changed −7 and +10 basis points, respectively.
Mechanism. The arithmetic separates nominal-yield movement from the real-yield benchmark. The par-curve differential is an inflation-compensation proxy, not a pure inflation forecast or a matched-security return.
Independent context and contradiction. Corporate-credit repricing did not establish uniform financing relief, although its different cutoff prevents a same-window causal claim. Nominal duration nevertheless benefited from falling nominal yields. Inflation-risk and liquidity premia can affect the differential without an equivalent change in expected inflation.
Confirmation: Comparable maturity and duration exposures, inflation-compensation measures and issuer funding terms establish whether nominal relief extends to real-rate and credit-sensitive financing conditions.
Falsification: Matched real yields and issuer funding costs subsequently decline with nominal yields, rejecting an interpretation of persistent divergence. The observed week’s decomposition remains intact.
Capital Consequence: Attribute nominal-rate, real-rate and credit-spread sensitivity separately. Do not reduce real-rate stress assumptions merely because nominal Treasury prices appreciate.
Structural Conclusion: One Treasury pricing channel eased; broader discount-rate relief was not established.
What Did VMSI™ Discover That Price Alone Did Not Reveal?
A market return cannot identify share creation, owner retention or financing access. The separate records exposed differences between these objects rather than a hidden institutional trade.
Their limits are equally informative. AUM accounting cannot validate conviction; an options model cannot identify dealer inventory; and lower nominal yields cannot establish lower real benchmarks.
The decision-useful advance is specifying which additional observation could change each interpretation, rather than calling every divergence a discovered mechanism.
Structural Conclusion: The report adds testable distinctions without claiming causal or ownership information the data do not contain.
The November 6 retrospective uses preceding-week earnings and revenue values of 30.1% and 13.6%. The dated-publication comparison above retains the original vintage rather than silently substituting those revisions.
A larger reported-company sample changes the blended estimate. It is not fixed-company growth acceleration or an equivalent upgrade to forward expectations. The 7.5% five-year earnings-surprise average concerns completed seasons, not an identical partial-season sample.
Structural Conclusion: Current-quarter delivery strengthened; a comparable broadening of forward expectations was not demonstrated.
Institutional Capital Migration Index™
Component
Score
Weekly Change
Trend
Interpretation
ETF Capital Flows
59.4
+2.7
Improving
Aggregate creations increased; beneficial-owner persistence remained unverified.
Dealer Positioning
45.5
−2.5
Defensive / Modeled
Broader modeled sensitivity deteriorated; actual inventories remained unobserved.
Liquidity Footprint
49.1
+1.6
Improving / Mixed
Reserves and funding-rate endpoints improved without establishing broad private financing access.
Credit Market Confirmation
45.7
−1.1
Weakening / Uneven
Locked-window widening contained substantial October 30 repricing and a CCC exception.
Cross-Asset Confirmation
44.7
−1.6
Divergent
Regional and defensive-market observations did not confirm synchronized accumulation.
ICMI™ Composite
48.9
−0.2
Defensive Capital Migration
Stronger implementation and reserve liquidity contrasted with weaker positioning, credit and cross-asset assessments.
The five components retain equal 20% weights. Their mean is 48.88, displayed as 48.9; the −0.2 change compares displayed composites, 48.9 versus 49.1.
Arithmetic consistency is separate from component calibration. The classification is not a measurement of aggregate institutional selling, and ICMI™ does not determine VMSI™ mathematically.
Structural Conclusion: The migration assessment remained defensive despite improved implementation and reserve conditions.
Institutional Capital Forensics™
The six IC-VMSI™ dimensions require different records. Ownership Stability concerns ultimate holders and retention; ETF portfolio holdings or shares outstanding alone cannot establish it. Passive Demand is informed by benchmark-linked implementation, without assuming every creation reflects a long-horizon allocation. Active Manager Demand requires active-allocation evidence, not inferred intent from style performance.
Flow Momentum has the clearest current confirmation. Market Absorption requires transaction costs, depth or price impact for comparable orders. Institutional Conviction requires behavior through changing conditions, not simply repeated aggregate issuance.
The sequence remains Alert → Absorption → Persistence → Confirmation. Its later stages are not established by the creation record. Missing observations limit confidence without constituting distribution.
ICMI™ Confirmation: Defensive Capital Migration; ownership and execution attribution remain incomplete.
Structural Conclusion: Share activity is observable more directly than who retained the exposure or how efficiently it could be traded.
Final Institutional Assessment
VMSI™ stands at 51.7 (−1.4), IC-VMSI™ at 64.4 (+0.4), and ICMI™ at 48.9 (−0.2). PLMT™ remains Fragile Stabilization.
The evidence does not justify treating stronger creations as completed accumulation, or weak prices and shrinking AUM as failed persistence. It supports a narrower conclusion: implementation improved while participation and several risk-pricing conditions became less favorable.
Three operational tests govern the next assessment. Exposure: reconcile net creations, share counts and valuation in a fixed fund universe, then evaluate beneficial ownership separately. Execution: compare depth, spreads and order impact under similar volatility and trading conditions, rather than infer capacity from gamma. Financing: distinguish reserve supply, secured borrowing prices, issuer spreads and real-yield benchmarks instead of using one as a proxy for all four.
These tests do not add scoring inputs, prescribe allocation thresholds or override the approved methodology. They define what evidence could strengthen or weaken the maintained interpretation.
ICMI™ Confirmation: Defensive Capital Migration, with stronger deployment and incomplete broader confirmation.
Structural Conclusion: The capacity to establish exposure was better evidenced than the ownership, financing and execution conditions supporting durable institutional expansion.
About VMSI™
VMSI™ — VICA Market State Index is an observational institutional framework designed to identify changes in the conditions shaping market behavior.
Rather than interpreting indicators independently, VMSI™ evaluates relationships among participation, liquidity, credit, positioning, volatility, capital deployment and global propagation.
Each weekly publication integrates observable evidence, proprietary relationship measures and structural validation to assess the prevailing institutional market state.
Scientific Standard
Observations measure conditions. Relationships reveal information. Patterns reveal structure. Independent confirmation strengthens confidence in a signal. Contradictory evidence defines its limits.
Maximum independent information—not maximum data volume. Correlated observations do not create artificial confirmation. Supplemental evidence supports falsification, contradiction testing, calibration, transmission analysis and metric-quality audit; it does not automatically become a scoring input.
Methodology changes require separate approval and prospective implementation.
Weekly evidence tests the framework’s implications; it does not prove the theory. Falsification conditions determine when an assessment must change.
IC-VMSI™ Definition
IC-VMSI™ measures institutional core capital-force and deployment behavior through observable allocation, creation-and-redemption activity, ownership structures, portfolio positioning and benchmark-linked investment behavior.
The framework does not attempt to identify individual institutional trades. Price, momentum, trading volume and price-driven AUM appreciation alone do not establish institutional capital deployment.
Underlying model construction remains proprietary to VICA Research.
Disclaimer / Trademark Notice
Disclaimer
VMSI™ is a proprietary observational market framework developed by VICA Research. This publication is provided for informational purposes only and does not constitute investment advice or a recommendation to buy or sell any security.
Conclusions reflect evidence-based interpretations of information available for the stated measurement period and may change as new evidence becomes available. Model assumptions, incomplete capital-flow attribution, missing dealer observations and differences in reporting conventions limit the precision of certain assessments.
Trademark Notice
VMSI™, IC-VMSI™, ICMI™, Institutional Capital Migration Index™, Institutional Capital Forensics™, Market Mechanics, PLMT, PIR™, CQR™, HPR™, DFR™, GPR™ and associated framework names are trademarks of VICA Research.